Two kinds of Colorado wind
Downslope windstorms roar off the Front Range foothills, especially in late fall and winter, with gusts that can top 100 mph in places like Boulder and the communities along the foothills. The December 30, 2021 windstorm that drove the Marshall Fire is the most destructive example in recent memory. Two weeks earlier, a December 15, 2021 wind event brought hurricane-force gusts across the eastern plains.
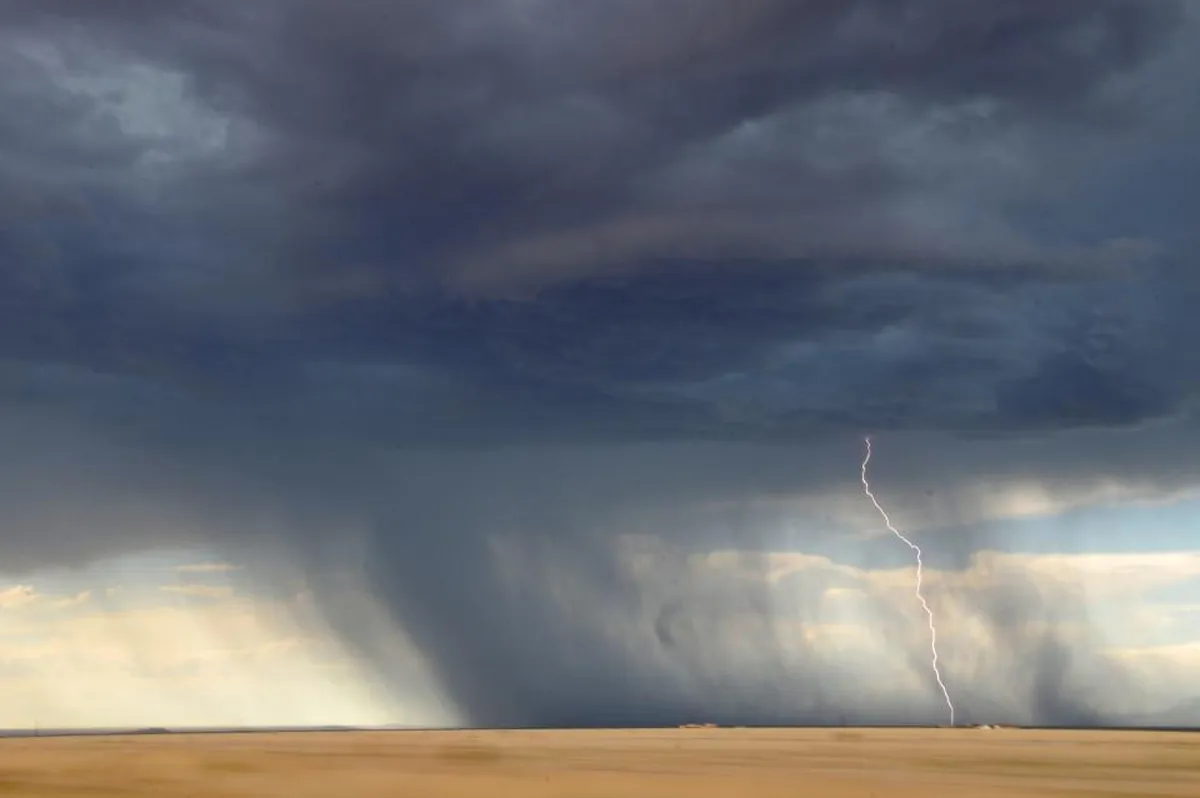
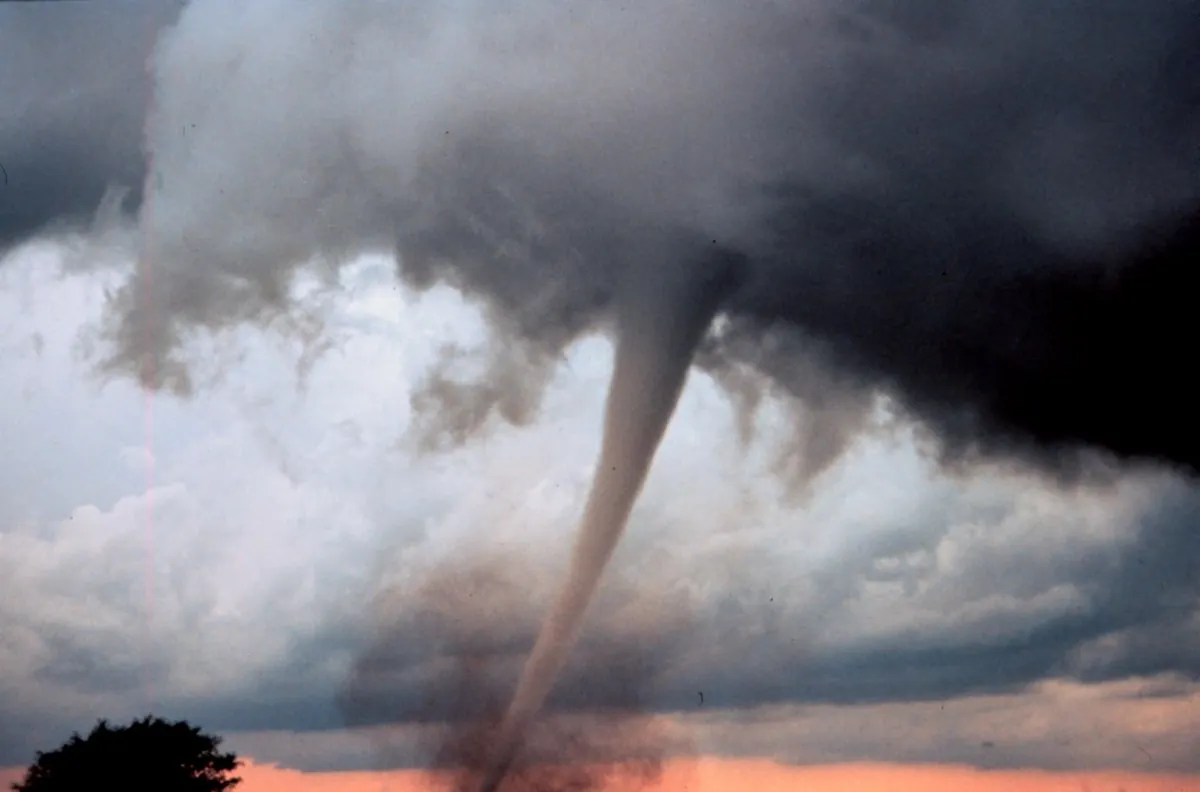
Thunderstorm winds and tornadoes are a plains and I-25 corridor risk from spring into summer. The May 22, 2008 Windsor tornado in Weld County showed how a single storm can damage hundreds of homes along its path.
Damage that gets missed
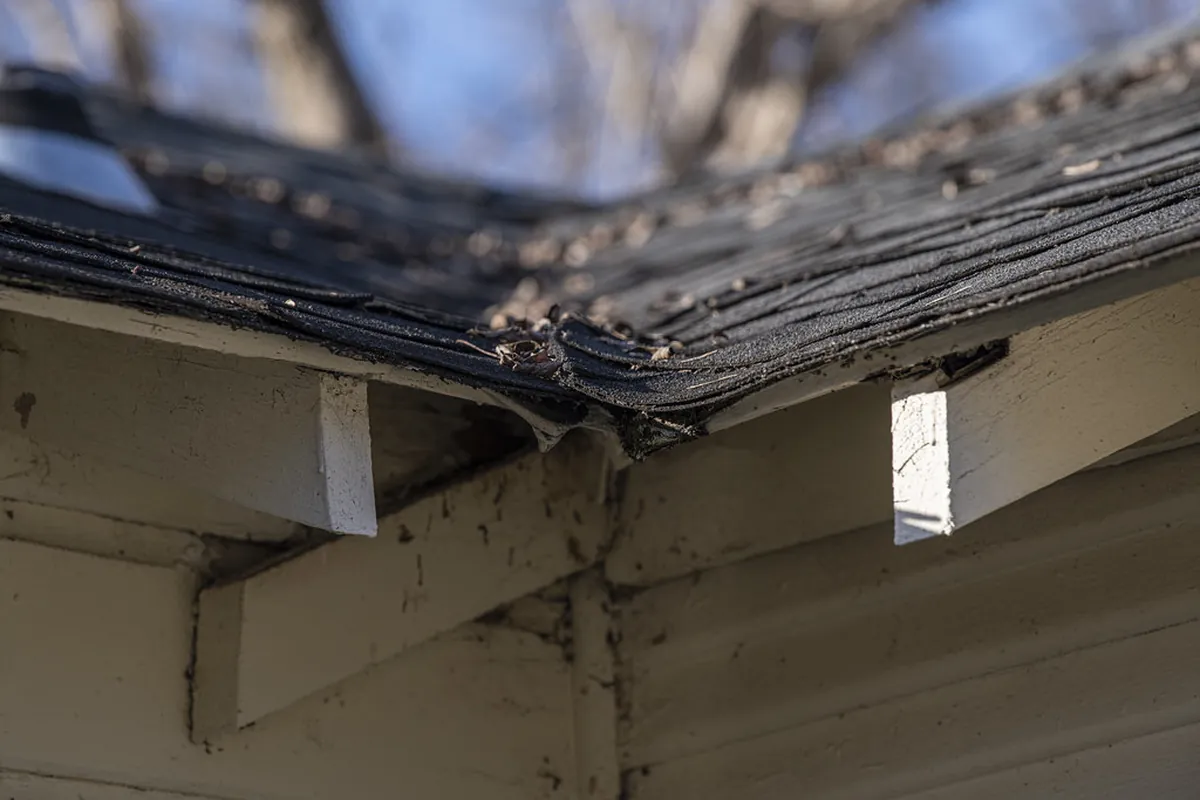
- Creased shingles. Wind lifts a tab, breaks the seal and creases the shingle; it lies flat again and looks fine from the ground.
- Unsealed courses across whole slopes that will fail in the next blow.
- Siding and soffit pulled loose, cracked or blown off on the windward side.
- Fences, decks and outbuildings, often handled under “other structures.”
- Interior water from wind-driven rain or snow entering through lifted flashing.
Wind versus wear and tear
Carriers often attribute lifted shingles to age or installation defects. Weather data, the pattern of damage relative to wind direction, and the condition of undamaged areas help separate storm damage from long-term deterioration. Appraisal can address the amount of loss; if the carrier denies wind damage as wear and tear, that coverage question may need a different path.
Common questions
Is wind damage subject to my hail deductible?
Many Colorado policies combine wind and hail under one percentage deductible. Check your declarations page to see how yours is written.
How do I prove the date of a windstorm?
Weather station data, local news coverage, neighbors’ claims and your own dated photos all help establish when the wind event happened.
Does appraisal cover fallen-tree damage from wind?
Damage to covered structures from a wind-thrown tree is usually part of the wind claim. Debris removal limits vary, so read that section of the policy.