Where homeowner estimates come up short
Most underpaid home claims aren’t denials. The adjuster accepted the loss, wrote an estimate and issued a check — and the check doesn’t match what contractors are quoting. The gap usually comes from a handful of familiar places:
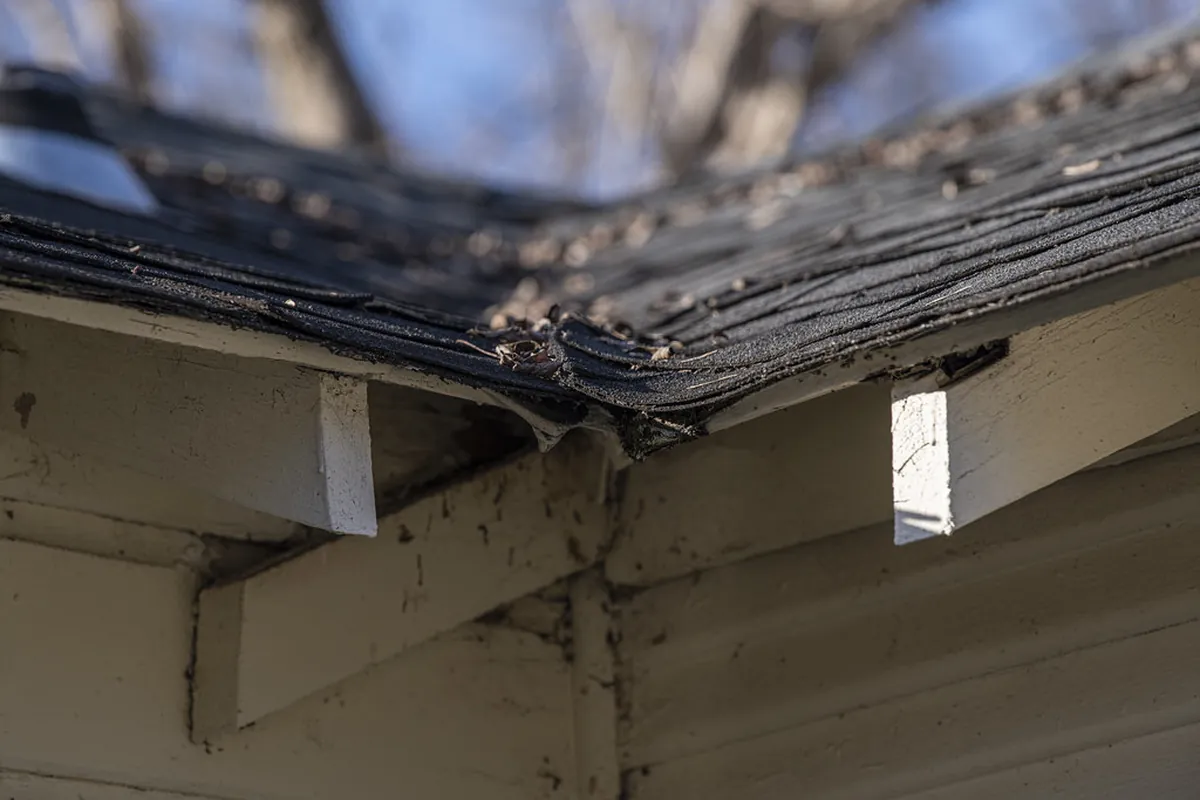
- Repair versus replace. A few shingles or siding panels priced as a patch when the material is discontinued or brittle.
- Matching. New flooring, cabinets or siding that won’t match what remains, leaving an obvious mismatch.
- Missing trades. Gutters, screens, paint, drywall texture, insulation, electrical or permit costs left off the scope.
- Code items. Ice-and-water barrier, drip edge, ventilation or other upgrades required at the time of repair and potentially covered under ordinance-or-law coverage.
- Overhead and profit. Omitted on jobs that plainly need a general contractor to coordinate several trades.
Condos and townhomes
Attached housing adds a layer: the association’s master policy and your HO-6 unit-owner policy each cover different parts of the building. Before anyone can value the loss, someone has to work out which policy pays for which item. We read the declarations, the master policy summary and the HOA documents so the scope lands on the right policy.
How a homeowner file runs
- A free call to understand the loss, the policy and where the claim stands.
- A review of the carrier’s estimate against your photos and contractor bids.
- Our own inspection and line-item estimate, priced for your area.
- A supplement request where that’s likely to close the gap — or appraisal where it isn’t.
Throughout, you’ll know what we found, what we think a panel will accept and what it costs to get there.
Common questions
Do I need my contractor’s estimate before calling?
It helps but isn’t required. The carrier’s estimate, your declarations page and photos are enough for a first look.
Will appraisal delay my repairs?
Not necessarily. Many owners make temporary repairs right away and schedule permanent work once the amount is settled. Photograph everything before work starts.
Can you help if the insurer already paid?
Yes. Payment doesn’t usually end your ability to dispute the amount, but deadlines in the policy still apply, so don’t wait.