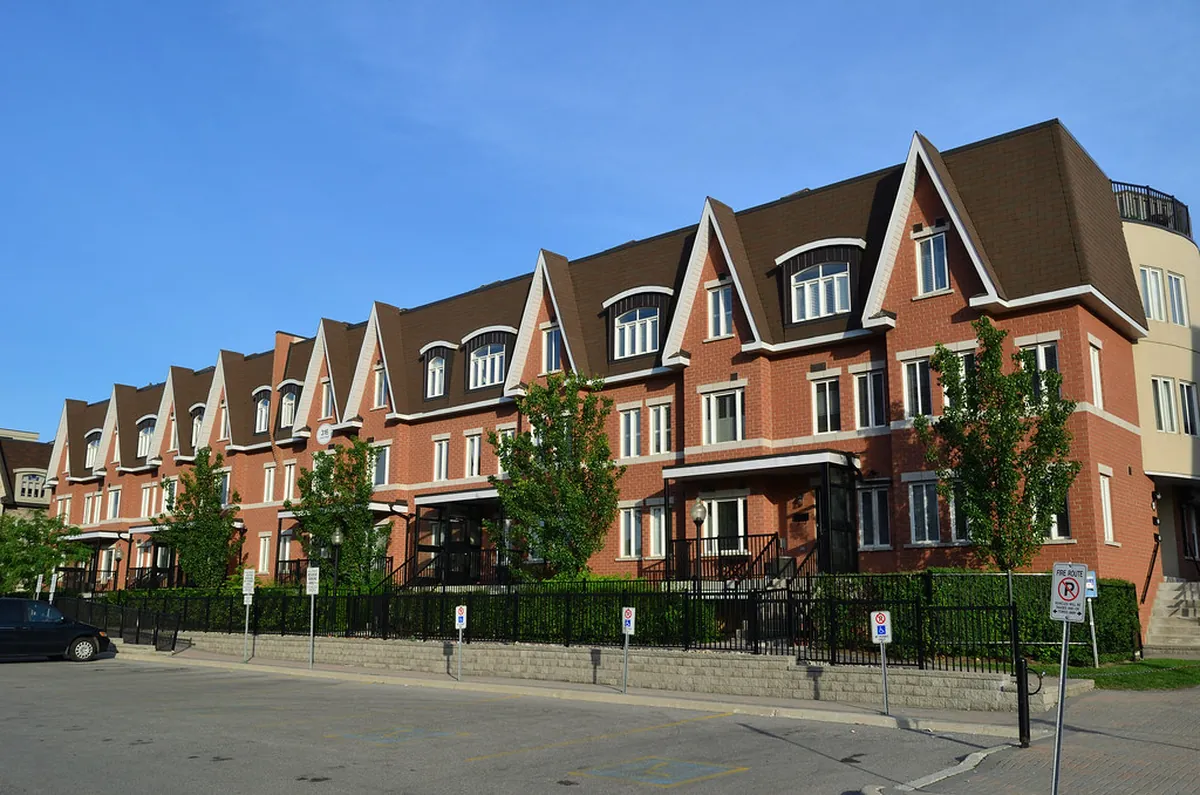
What makes commercial and association claims different
Commercial policies are rarely one-size-fits-all. Blanket limits, scheduled buildings, coinsurance, ordinance-or-law sublimits and separate wind/hail deductibles all shape what a claim is worth. Associations add bylaws and declarations that split responsibility between the HOA and individual owners. Before arguing about price, the scope has to be right.
Where large estimates go wrong
- Sampling instead of inspecting. A carrier inspects a few buildings and applies the result to the rest. Damage often varies by exposure, roof age and material.
- Low-slope roofing. TPO, EPDM, modified bitumen and built-up systems hide damage that needs core samples or moisture surveys to find.
- Matching across buildings. Replacing some buildings’ siding or roofing but not others can leave a community visibly mismatched.
- Code and permitting. Commercial repairs can trigger energy-code insulation, drainage or accessibility work that a quick estimate misses.
- General conditions. Supervision, equipment, dumpsters, temporary protection and phasing around occupied units.
How we organize a large file
We build a building-by-building scope with consistent photos, measurements and roof diagrams, then roll it into a summary that a board, property manager or umpire can follow. For associations, we can present findings to the board in plain language and keep the documentation tidy for owners and lenders.
Board decisions
Invoking appraisal is a significant decision for an association. We can explain the process to the board, but questions about authority, governing documents and litigation belong with the HOA’s attorney.
Common questions
Do you work directly for HOA boards?
Yes, and alongside property managers and association attorneys. Engagement is with the association or owner who holds the policy.
Can you handle low-slope commercial roofs?
Yes. We coordinate testing such as core samples or moisture scans when visual inspection isn’t enough to document damage.
What about business income losses?
Appraisal can sometimes include business income or rental loss if the policy allows, but those calculations often need an accountant. We’ll tell you what we can and can’t value.